Heresy
Pearl and the Resurrection of Bitcoin
By
Brian Breslow
No Limit Holdings is generationally long Pearl on the thesis it can be the next Bitcoin. Here’s why...
Bitcoin is a religion. It has scripture, prophets, apostles, an immaculate conception, and the most devout congregation in finance.
Orthodox doctrine holds computational waste as one of its most sacred teachings. Not merely an unfortunate side effect of proof-of-work, but a requirement for hard money.
This is wrong.
Despite my humble beginnings as a disciple of Satoshi, I've become a heretic. A harder form of money can exist. One where useful AI work is objective, expensive to perform, and cheap to verify, just like Bitcoin work, except without the computational waste. This will birth a new religion, creating a rare opportunity for a second immaculate conception.
In Christianity, the Paschal Mystery treats Christ’s suffering, death, resurrection and ascension not as independent events, but as one continuous act of redemption.
Pearl made me start thinking about Bitcoin the same way.
The waste, the security budget decay, the migration of Bitcoin miners to AI, and the emergence of proof-of-useful-work look like separate stories.
I increasingly think they are chapters of the same one. The Book of Pearl.
The Original Sin
“Bitcoin wastes compute”
That was how our conversation began. We spent the next hour discussing whether proof-of-work could be redesigned so the computation securing the network wasn't merely burned, but useful somewhere else. Said differently, the solution to any SHA-256 hash means nothing and is used for nothing, aside from securing Bitcoin. In essence, it is waste. It cannot be recycled. Currently there are nearly 1,000 EH/s, or 175 TWh of annual power draw being purposefully “wasted” to secure the Bitcoin network. This is roughly equivalent to the total annual electricity consumption of a midsized country like Sweden or Poland.
The waste is intentional. Its sunk cost is exactly what prevents malicious miners from controlling the network at trivial cost. But what if we could replace SHA-256 with a different algorithm? A more useful one. One where the cost to attack the network remains high, but the work itself is also useful as a standalone.
“proof of useful work” we whispered together.
The concept was elegant and powerful. His project, a new PoW Layer-1, was designed to make miners compete around AI inference instead of a meaningless hash puzzle. In other words: recreate the economic skeleton of Bitcoin, but replace the useless computation with AI work somebody actually wants.
The problem is that “useful” work is much messier than SHA-256. The work still needs to be expensive to perform, but the answer also needs to be objective and cheap for everyone else to verify. Bitcoin nails this asymmetry: mining is brutally expensive; verification is basically free. Proof-of-useful-work (PoUW) had never nailed both at once.
Bittensor: The False Prophet
I’m seduced by proof-of-useful-work. You could not manufacture a better narrative if you tried. As you go down this rabbit hole, the first thing you discover is Bittensor which already tried to become the canonical “AI Bitcoin”: a scarce native token, miners supplying AI-related resources, validators judging output, and emissions flowing to whoever the network deemed valuable.
Sounds good in theory. The problem is the phrase “deemed valuable.”
There is a simple beauty in Bitcoin’s useless work: nobody has to debate whether the hash was useful enough. Miners do not need a committee, a scoring rubric, or an economic vote to decide who did the best work. The answer either satisfies the target or it does not.
Bittensor necessarily introduces more judgment. Its incentive system has evolved materially over time as the network has tried to improve how value is measured and how emissions are allocated. That may be completely reasonable for an AI coordination network. I just don’t think it is how you build money.
This subjectivity of Bittensor’s consensus, named Yuma, also has a track record of collusion within the network, specifically because validators are incentivized to work together to vote on usefulness. Another non-starter for an asset aspiring to be trusted money.

Bittensor has seen numerous protocol level economic changes. dTAO barely lasted longer than one year before it was changed again to the current “TaoFlow” model
The hard problem is making useful work behave like Bitcoin work.
Bitcoin Work has Four “Money” Qualities

The work has to be expensive and objective. There cannot be a subjective score attached to the winning block.
The work has to be cheap to verify. A laptop should be able to reject a dishonest hyperscaler.
Consensus cannot be required to determine what “useful” means. The moment it does, you have introduced an oracle, a vote, or a governance surface.
The monetary rules must be ossified. Upgradability is useful for software; predictability is required for money.
The Resurrection
These pitfalls were fresh on my mind as He finally revealed the name of His AI PoW creation. Pearl. The pitch sounded almost suspiciously obvious: fork Bitcoin, replace SHA-256 with matrix multiplication, and make the same GPU operation produce both AI output and proof-of-work. The thing that made me pay attention was not the “AI mining” part. People have been pitching useful mining since Bittensor. It was the verification construction:
Pearl’s core research shows how arbitrary matrix multiplication can be turned into proof-of-work with asymptotically negligible proving overhead, subject to a new computational hardness assumption around low-rank-noised matrix multiplication. The implementation then wraps the winning work in a compact zero-knowledge block-opening proof so ordinary network nodes do not have to rerun an H100-sized job just to validate a block.
Again, but this time in English: Pearl had figured out a way to make AI work cheaply and quickly verifiable, just like Bitcoin work.
That is the unlock.
What is Matrix Multiplication?
Large Language Models (LLMs) are built on top of artificial neural networks. These neural networks are mostly built using a transformer based architecture (popularized in the landmark research “Attention is All You Need” circa 2017). Transformers use layers of nodes, weights, and mathematical functions to process data, and form the backbone of modern large language models like GPT or Claude.
Transformers carry grids of numbers called activations through layer after layer of learned weight matrices. Each layer repeatedly multiplies activations by weights, transforms the result, then feeds it forward. The arithmetic primitive underneath an enormous amount of this work is matrix multiplication, or MatMul. GPUs are basically giant MatMul machines, and these algorithms are what make AI possible. Every modern LLM, image model, and AI agent ultimately spends an enormous amount of its compute budget pushing matrices through these kernels. (A kernel is a primary block of code which runs on a GPU and tells it how to function and start).
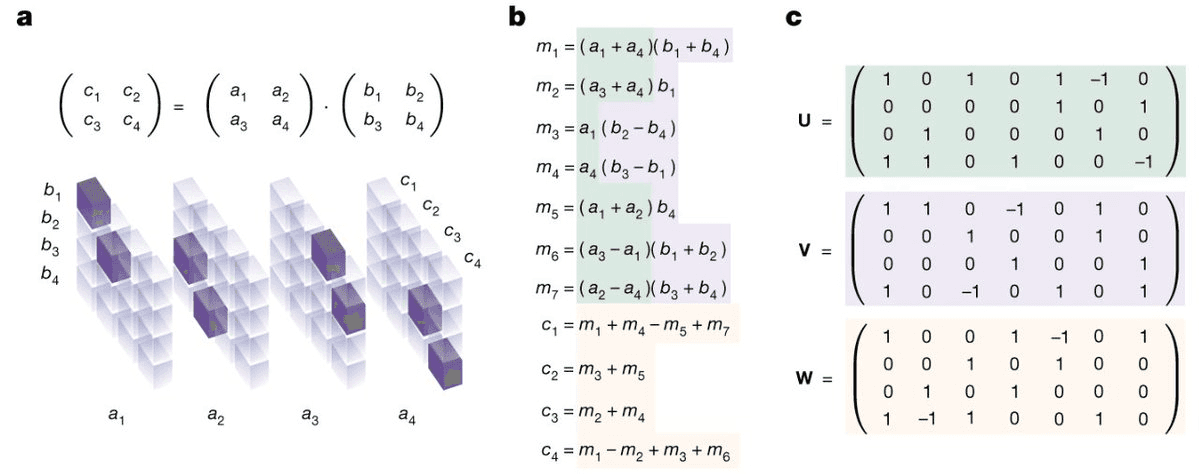
Matrix Multiplication (MatMul)
MatMul shares a lot in common with SHA-256. It requires significant compute to solve quickly, the solutions to the algorithm are not subjective, they cannot be forged or guessed (nor can you guess ahead of time what the next block’s function will be). However, there is one stark difference. While SHA-256 has no practical use-case aside from securing the Bitcoin network, matrix multiplication is what powers AI. It stands to reason we should fork Bitcoin and replace SHA-256 with MatMul for the proof-of-work mechanism. Then, this new “MatMul Bitcoin” could be decentralized and secured similarly to Bitcoin, but the same work going into securing the network is also useful to AI applications outside of the network.
This is exactly what Pearl built.
So how does this work in practice?
Think of Pearl as attaching a tamper-proof lottery ticket to an AI job before the GPU runs it. First, the miner cryptographically seals the matrices it intends to multiply, so it cannot swap them out later. Then the network adds a small, unpredictable mathematical “watermark” derived from the latest chain state. The GPU performs essentially the same matrix multiplication the AI workload already needed, but now each run is unique and impossible to precompute.
As the GPU works through the multiplication, it leaves behind a transcript of what it did. If one of those pieces of work happens to satisfy Pearl’s difficulty target, the miner has found a block. The key part is that Pearl’s watermark is cheap to mathematically peel back off afterward, leaving the original useful AI result intact. This is the major innovation of Pearl: how to make MatMul cheaply verifiable like SHA-256.
More technically: Pearl commits to the input matrices with BLAKE3, derives pseudorandom low-rank noise from the chain state, performs the noise-perturbed tiled MatMul, and records a mining transcript that can be proven if the difficulty predicate is hit.

Adapted from “The Genesis of Pearl” - Ilan Komargodski
One might say well wait hold on, to prove the miner actually performed the committed work, you would have to reveal rows and columns of the matrices, which is still compute heavy and could leak proprietary model weights.
Pearl solves this second problem with a ZK-SNARK block-opening proof. The prover demonstrates that it knows private matrix data consistent with the commitments and that the winning tile satisfies the mining predicate, while the network sees only a compact certificate. This final recursive proof is under 60KB. In theory, this is also what makes closed-source lab adoption possible: the protocol does not require a lab to publish its weights just because it mines.
Expensive to produce, cheap to verify, objective consensus, and predictable rules. These are the Bitcoin-like properties every prior useful-work design failed to solve for.
The Useful-Work Meme
There is one important criticism of Pearl that is technically correct but, in my view, entirely misses the economic design.
The base protocol does not explicitly prove that a matrix multiplication came from a paying inference customer. A miner can feed the protocol synthetic matrices and still do valid PoUW and earn Pearl rewards.
In fact, an empirical paper published this summer measured the early Pearl network and argued that the dominant mining software at the time was producing verifiable MatMul but no external inference output.
However, what this critique fails to realize is that this is the entire point.
If PoW consensus has to ask “was this inference actually useful?” you are back in the subjective world we sought to escape. You would need a subjective decision, a vote, a validator score, or some semantic definition of usefulness, which is something that can be gamed, colluded around, or changed arbitrarily.
Instead, Pearl takes a game theoretic approach to mining. Pearl still verifies the objective thing it can verify: expensive MatMul, but then simply allows the market to organically enforce useful work vs explicitly checking for it.
A pure 1:1 miner (i.e. a “non-useful” miner) has to pay the full GPU cost to earn PRL. A duplex miner (a miner who is both mining and serving useful inference) is already being paid by a customer for the AI workload and only has to absorb Pearl’s incremental overhead. As competition and Pearl network difficulty rise, the full-cost miner should be the marginal producer and eventually gets squeezed by the useful miner whose customer is already paying most of the power bill.
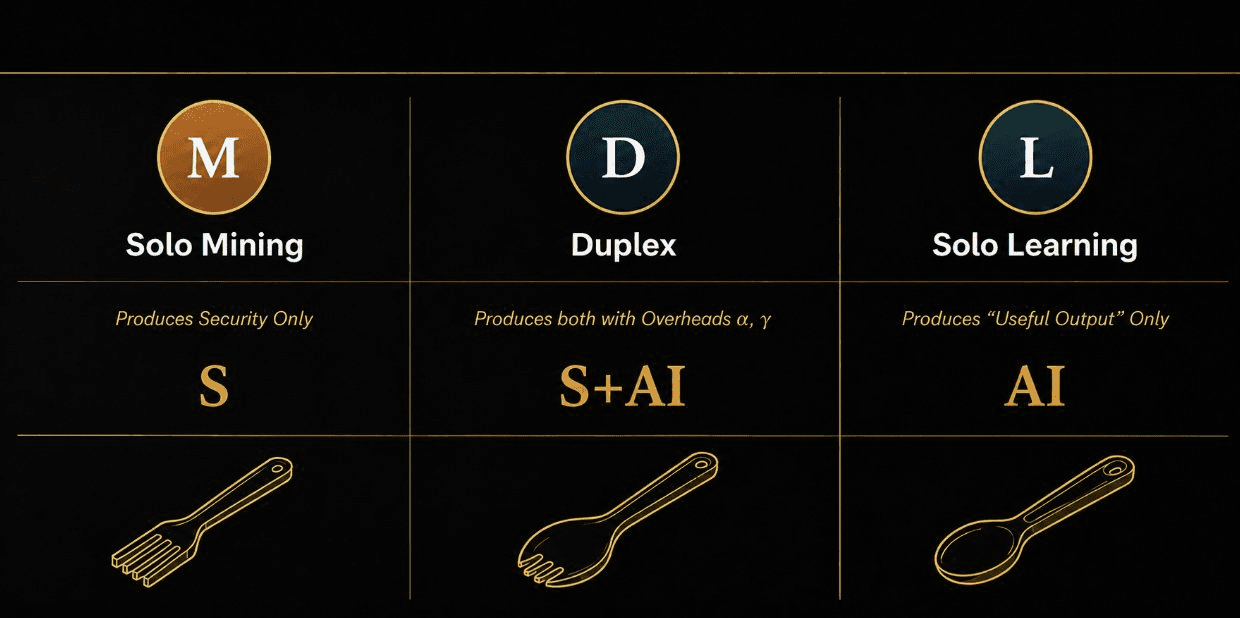
Adapted from “The Economics of Proof-of-Useful-Work” - Rafael Pass
Said another way, once enough useful miners are participating in the network, non-useful miners won’t be able to profitably mine Pearl, and won’t have any incentive to continue mining.
In this manner, Pearl looks a lot like Bitcoin. The network doesn’t actually care what useful work is, or what counts as useful work, it's simply that the economic reality enforces that useful work gets done by the miners. This setup drastically reduces the collusion risk of Pearl miners, which makes Pearl a trustless and fair network like Bitcoin.
So the question is not “does Pearl force useful work today?” It does not. The question is whether overhead gets low enough that useful miners become the structurally lowest-cost producers.
The Entire Ballgame is Overhead
Once you see Pearl this way, the project becomes much easier to understand. Forget the philosophical argument over PoUW for a second. There is only one thing that matters: incremental overhead, which is the additional cost and latency incurred after integrating with Pearl’s 2:1 kernel.
Pearl currently reports +5.08% end-to-end overhead on Llama 70B running across four H200s and +3.9% on DeepSeek V3.2 across eight H200s versus the stock serving engines. The current production path uses integer W7A7 quantization; native floating-point support is still under development.

Adapted from “The Genesis of Pearl” - Ilan Komargodski
While Bitcoin’s hashrate grows so long as the block reward is greater than the cost of mining, Pearl’s hashrate grows so long as its block reward is greater than lost revenue from AI inference from adopting Pearl (i.e. the overhead).
Five percent is not “free.” In volatile crypto markets, five percent sounds like a rounding error. In an inference fleet running at thin gross margins, it is real money. But it is already within the range where a block-reward subsidy can plausibly compensate a provider, and the roadmap is explicitly about pushing the number toward zero.

At 0% overhead, the game becomes obvious. If two otherwise identical inference providers sell the same tokens at the same price, and one of them earns PRL on top with no meaningful degradation in throughput, the non-mining provider is voluntarily leaving money on the table. Competition should force adoption.
Pearl does not actually need to hit mathematical zero overhead for this to start. It needs the PRL subsidy, net of integration friction and risk, to be worth more than the lost throughput and engineering cost (the overhead).
The Chess Grandmaster Problem
There is an obvious problem with everything I just said.
If Pearl succeeds in driving mining overhead toward 0%, haven’t we also driven the cost of attacking Pearl toward 0%? An attacker could rent a pile of GPUs, attack the network, and simultaneously sell the inference those same GPUs are producing. Did we just invent a blockchain that pays you to attack it?
This sounds convincing. It is also wrong.
Rafael Pass, a MIT PhD, Cornell professor, and core advisor to Pearl Research Labs uses a chess analogy to understand why in his landmark paper, The Economics of Proof-of-Useful-Work.
Imagine I play two chess matches against two grandmasters. I am white in one game and black in the other. If I actually play both games myself, I am obviously getting smoked twice (my chess skills do not compare to a grandmaster).
Clearly, I need to alter my strategy. A strange idea comes to me… what if I play both games at the same time! This way, I wait for Grandmaster A to make the first move, then play that exact move against Grandmaster B. Whatever B responds, I carry back and play against A. I just keep doing this. From each grandmaster’s perspective they are playing me. In reality, the two grandmasters are playing each other through me.

If A wins, I lose one game and win the other. If they draw, I draw both. Either way, by linking two games together I have guaranteed myself at least one non-loss, despite having essentially zero chance of achieving that result if you analyzed each game independently.
This is the same mistake people make when they analyze inference and Pearl mining as two independent businesses. You cannot. They are one joint economic system.
Say $1.00 of GPU work produces an inference job. Before Pearl, the provider needs roughly $1.00 of inference revenue to cover the compute cost. Now assume the same work also earns $0.20 of PRL. A duplex provider (who is both selling inference and mining Pearl) can sell the inference for $0.80, earn the PRL worth $0.20, and still break even at their $1 compute cost:
Instead of earning $1.20 forever, competition should eventually push that $0.20 PRL subsidy into the price of inference.
So the equilibrium starts to look like:
$0.80 inference + $0.20 PRL = $1.00 of compute cost
Now imagine an attacker shows up.
The attacker has the same GPU economics as everyone else. While attacking Pearl, he can still sell the useful inference produced by those GPUs for $0.80.
So at first glance, the attack seems almost free:
He spends $1.00 on compute. He earns $0.80 selling inference.
And normally he would expect another $0.20 in PRL.
That last $0.20 is where the security comes from.
A successful 51% attack is not normal mining. The attacker is trying to damage the very network whose token is supposed to pay him. He cannot safely assume the PRL earned during the attack will still be worth the pre-attack price.
So strip the PRL reward out of the attacker's recovery:
$1.00 compute cost − $0.80 inference revenue = $0.20 attack cost
That $0.20 is the security budget.
Now let’s scale up this example:
Imagine the entire Pearl network represents 100 units of compute.
Each unit costs $1.00 to operate and earns:
$0.80 from inference
$0.20 from PRL
Across the whole network, Pearl is therefore paying:
100 × $0.20 = $20 of block-reward subsidy
The attacker needs to control half the network to break the honest-majority assumption, so he needs 50 units of compute.
Those 50 units cost $50 to run, but he can recover $40 by selling the useful inference:
$50 compute − $40 inference revenue = $10 net attack cost
What is $10?
It is exactly half of the network's $20 Pearl reward budget.
Pass proves that the cost to attack Pearl is exactly the same as Bitcoin. I.e.:
Attack cost = Block subsidy / 2
This is the subtle but incredibly important point: the marginal technical cost of adding Pearl mining on top of inference can approach zero without the economic cost of acquiring Pearl security approaching zero. The subsidy gets competed away somewhere else in the system. In this case, into cheaper inference.
This is also where proof-of-useful-work gets really interesting. If the block reward is competed into inference prices, Pearl is not simply attaching a token to an existing compute market. It is changing the cost curve of the compute market itself. Pass describes this further in his Duplexia Framework.
The Gospel
Pass gives names to the equilibrium progression sitting underneath the chess example.
Bitconia: Pearl behaves like ordinary proof-of-work. Miners compete because the block reward pays them. Useful inference is economically separate.
Fortessia: Duplex providers begin replacing pure miners. The same amount of AI work gets done, but more of it also secures the chain. Security rises without needing a proportional increase in otherwise-wasted compute. (Pearl is here today).
Duplexia: The token subsidy becomes meaningful enough relative to inference economics that providers can lower effective inference prices while preserving economics. Lower prices stimulate more inference demand, which produces more duplex compute, which can increase security again.

Adapted from “The Economics of Proof-of-Useful-Work” - Rafael Pass
The block reward can subsidize useful work and reshape inference prices without severing the link between economic security and the reward budget. In other words, Pearl adoption by AI labs can materially accelerate demand for AI, thus kicking off an adoption flywheel via Jevons Paradox.
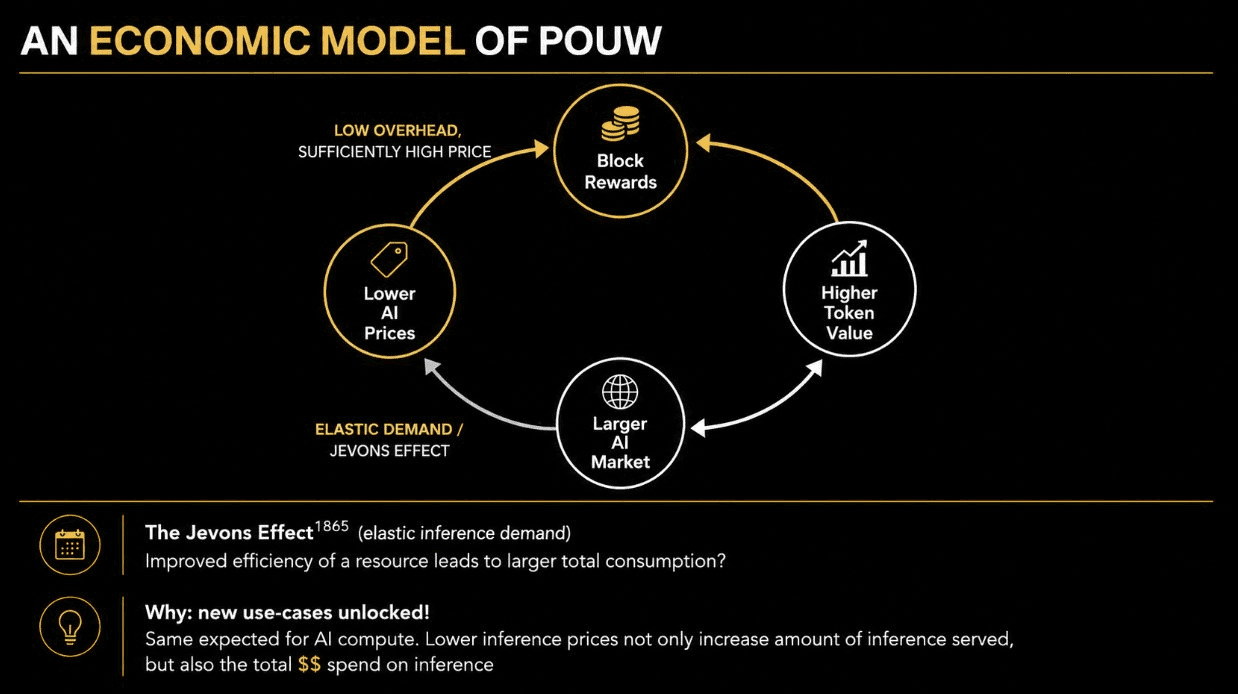
Adapted from “The Economics of Proof-of-Useful-Work” - Rafael Pass
Miracles Require Evidence
In May, Together AI launched a Pearl-powered Gemma endpoint at more than a 25% discount, explicitly because they are mining Pearl with the 2:1 kernel integration. Together said it plans to expand the Pearl-powered product portfolio and potentially pass a portion of emissions directly to customers.
Read that again. You can buy cheaper inference today because the GPU producing your tokens is mining Pearl at the same time.
Pearl itself now operates an OpenAI-compatible production inference platform across distributed Pearl GPU capacity. The platform currently serves open-weight models and charges ordinary prepaid USD credits. Today AI goes in and PRL comes out. The eventual bull case is when the loop closes: PRL goes in and AI comes out.
I would describe Pearl as having crossed into Fortessia. Commercial duplex work exists. What has not happened yet is the harder thing: duplex work becoming the dominant marginal producer across the network.
Pearl Tokenomics
Pearl is a fork of Bitcoin. There is a redenomination of supply (2.1B max supply vs 21M), and a block-after-block smooth emissions decay curve vs fixed four year halvings. Outside of these mostly cosmetic changes, the tokenomics should look very familiar to you.
Roughly half of all PRL is scheduled to be emitted by block 650,226, approximately four years at target block time, and issuance then decays continuously with a long finite tail.

Pearl’s cumulative emission under the whitepaper schedule. The curve is smooth rather than stepwise
The Immaculate Conception and a Defense of Ossification
Ossification is crucial for money-fication. It might sound counter-intuitive given what we know about future-proofing and the benefits of upgradability (just look at the tension related to Bitcoin’s lack of quantum resistance today), but for cryptomoney stores-of-value, ossification is paramount.
Historically, ossification has prevented Bitcoin from being captured by special interests or mutating unpredictably. It also minimizes bug risk and establishes a narrow predictable foundation, allowing institutions to build financial infrastructure with minimal risk of rules changing beneath them. For example, see the current Ethereum war over emission reduction as a prime case study.
Most importantly, ossification creates monetary soundness: making supply caps and issuance rules permanent and mathematically indisputable without requiring ongoing trust in core developers. This prevents future alteration of rules by political interests, mining cartels, or corporate desire. The massive coordination weight required to change an ossified network ensures it remains resistant to state-level coercion or regulatory capture.
If we want to truly create decentralized AI-backed money, ossification is critical.
This is where I think Bittensor permanently disqualified itself from being AI money. It can be an AI coordination layer, incentive network, or smart-contract platform. Value can still flow to $TAO. But a monetary asset whose economic policy repeatedly changes in response to political and market pressures is not hard money. Other proof-of-useful-work competitors pivoting to MatMul cannot simply become AI money either. For example, a PoW chain called Nockchain, which uses ZK proofs to verify different PoW puzzles, recently announced a pivot into MatMul based puzzles for their miners. Their new “National Compute Company” attempts to position Nock as a tokenized version of compute and a form of AI money.
But, you cannot simply wake up one morning and decide you were born as AI money. So what, the first 126,000 blocks (over 50% of token supply) before the pivot are not AI money, but the tokens after the pivot are? It should be obvious why that is different from an asset whose monetary identity was built around AI work from genesis.
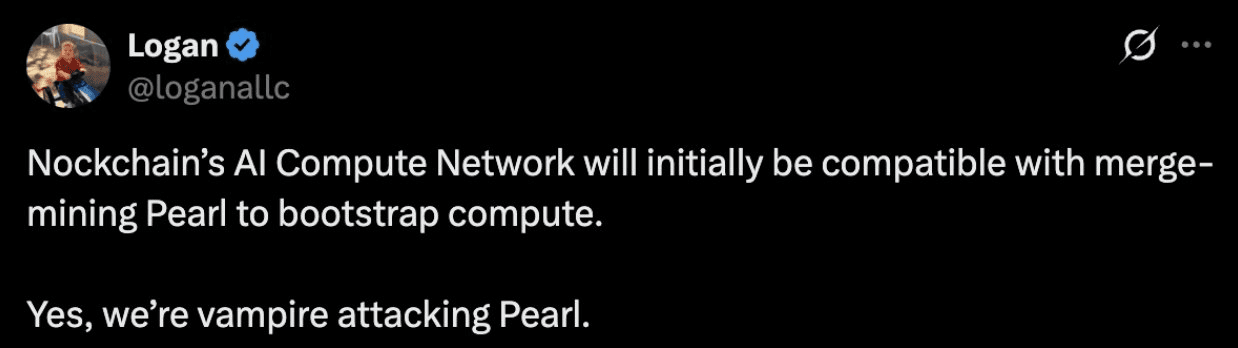
Nock so badly wants to be Pearl lol
With Pearl, institutions can build around the assumption that the monetary kernel will not mutate underneath them.
To be fair, Pearl is not ossified today. It is a months-old chain with planned floating-point upgrades, evolving server integrations, a future marketplace concept, and other active protocol work. Calling it already ossified would be a stretch.
But, Pearl has a deterministic monetary schedule and an architecture that can eventually converge on a narrow, stable monetary kernel. The requirement is that the upgrade cadence slows as the important AI compatibility problems are solved. If Pearl turns into a permanently governed science project, my “AI money” thesis breaks.
The Passion of Bitcoin
The economic singularity has Hawking radiation. What is really ironic about studying Pearl is that you finally realize what is necessary to solve Bitcoin’s long-term security budget problem.
Bitcoin’s network transaction fees are nowhere near enough to incentivize the continued block production of Bitcoin after all 21M BTC are mined and the block subsidy ends. Granted, it is estimated the final Bitcoin won’t be mined until year 2140, so it seems we’ve a long way to go until this becomes an acute problem. However, this is false hope. This same pressure actually arrives every halving, but Bitcoin has historically escaped because price appreciation repeatedly recapitalized the mining industry.
Era | Subsidy | Miner Revenue vs. Today |
|---|---|---|
2026 | 3.125 BTC | 100% |
2028 | 1.56 | 50% |
2032 | 0.78 | 26% |
2036 | 0.39 | 13% |
2040 | 0.195 | 7% |
2048 | 0.049 | 2% |
2052 | 0.024 | 1.5% |
Transaction fees today are approx. 0.7% of miner revenue. Miners are overwhelmingly subsidized by block rewards. The table above illustrates that at a constant BTC price, as block subsidy declines after subsequent halvings, miner profitability will be put under significant duress.
In other words, miner sustainability is entirely dependent on the price of Bitcoin going up in perpetuity. This is an optimistically virtuous cycle as higher BTC price encourages more miners to join the network, creating more hashrate, and thus more economic security to the network.
In a competitive mining market, expected mining revenue should eventually get competed down toward the marginal miner's cost of production. When Bitcoin's price rises, the dollar value of the block reward rises with it, attracting more hashrate until difficulty and competition compress those excess returns. Historically, this has correlated the price of BTC with hashrate.

However, Bitcoin hashrate is now in secular decline.
The rise of AI has created an alternative outlet for trapped energy… AI compute. Miners are increasingly pivoting from mining Bitcoin, to serving AI workloads instead. In practical terms, this means they are shutting down their ASICs, and instead filling their datacenters with GPUs, and then renting them out to AI companies to operate the GPUs. Bitcoin miners are becoming landlords. The most notable example of this is actually a previous Ethereum miner, CoreWeave, who pivoted to AI post “The Merge”, but the trend extends far beyond just them. Within the universe of publicly traded Bitcoin miners (IREN, Core Scientific, Applied Digital, TeraWulf, HIVE, Bitdeer, Riot, Cipher, Cleanspark, MARA, etc.), serving AI workloads is expected to contribute 70%+ of their revenue by 2028, as compared to <2% in 2024.

The evidence is in their public disclosures. In 2025, IREN generated just $16.4M of AI Cloud revenue on $501M total revenue; Core generated $65.4M of colocation revenue on $319M total; HIVE generated ~$10M of HPC revenue on $115M total; and TeraWulf generated $16.9M of HPC revenue on $168.5M total.
The big traditional miners were also essentially 0% AI revenue in 2025: MARA generated $907.1M, CleanSpark $766.3M, Riot $647.4M and Cipher $223.9M, all from Bitcoin mining and adjacent legacy businesses rather than AI.
Already in the current year (2026) there’s a remarkable divergence. Core and TeraWulf aren't really Bitcoin miners from a revenue-mix perspective anymore. Core said HPC colocation represented 77% of revenue in 1H26 and 83% in Q2; TeraWulf reported 71% of Q2 revenue from HPC leases.
IREN is even more dramatic. The company is now targeting more than $4B of AI Cloud ARR by the end of calendar 2026, with ~85% of that target contracted as of July.
Given the overwhelming backlog of signed AI contracts ($135B+), this transformation will be fully complete by 2028.
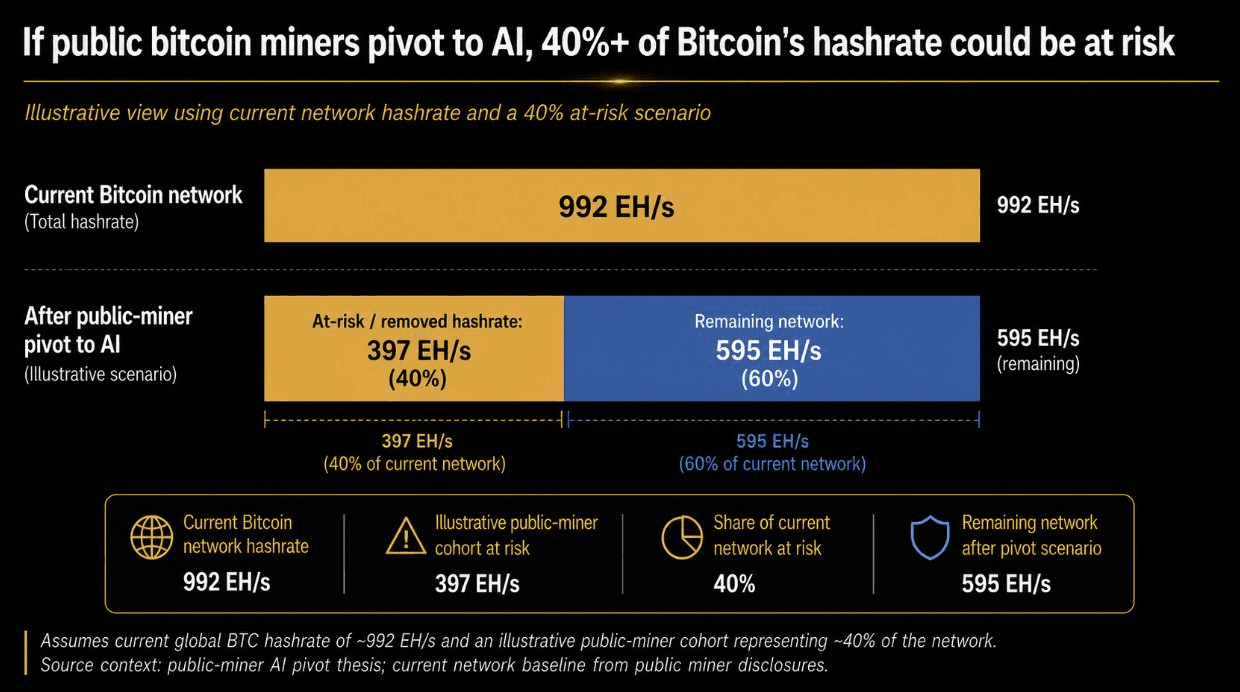
If all publicly traded Bitcoin miners continue the trend of pivoting to AI, this would cause Bitcoin to lose nearly 40% of its current hashrate.
This perverts the previously strong incentives of the Bitcoin network. In the past when Bitcoin price would decrease, miners would drop off the network as they became unprofitable, hashrate would drop, and mining difficulty would adjust accordingly until it was profitable to mine Bitcoin again, in which case hashrate would rise and the price of Bitcoin would increase again.
This time around, even if the price of Bitcoin goes up, these miners cannot easily rejoin the network as now they are landlords with AI tenants, who are signed on long-term leases (typically 10+ years). Therefore, I expect the hashrate of Bitcoin to remain stagnant or down even if the price of Bitcoin increases. This is why I say Bitcoin hashrate is in a secular decline; the miner pivot to AI is sticky.
These trends illustrate the structural difference in Pearl's 2:1 model. A Pearl miner's primary economics come from serving AI; PRL is incremental. If mining overhead approaches zero, an inference provider whose customer already paid for the GPU and electricity has little economic reason to stop producing Pearl work even as PRL emissions become less valuable. Turning Pearl off doesn't meaningfully save anything.
Bitcoin does not have this luxury. Its miners exist because Bitcoin pays them to exist. When the reward stops covering the machine and the power bill, the machine shuts off. Pearl's useful compute can remain online because somebody wanted the computation anyway. This means the physical compute securing Pearl can be dramatically stickier than Bitcoin's dedicated mining fleet.
The Ascension
The trillion dollar question is obviously what this thing should be worth. In my view, the market opportunity for Pearl is enormous, with a TAM even larger than Bitcoin. Let me elaborate.
Today, Bitcoin’s hashrate is approx. 920 EH/s while Pearl’s is 24 EH/s. This isn’t apples-to-apples as the underlying work algorithm is different. It would be like comparing horsepower to kilowatts. To properly compare Bitcoin hashrate vs Pearl hashrate, we need to dive a layer deeper and compare the implied power draw of all the hardware securing each network. Using an all-in Bitcoin network electrical intensity of roughly 18.3 J/TH (based on current ASIC hardware), 920 EH/s implies about 16.8 GW of continuous load, or roughly 147 TWh annually. For Pearl, we can map a 24 EH/s network to roughly 320,000 GPU-equivalents and 112 MW of GPU silicon draw. Gross that up by 1.55x for host systems, cooling, networking and facility overhead and you get roughly 174 MW at the meter, or ~1.5 TWh annually.
On those assumptions, Pearl’s electrical footprint today is roughly 1% of Bitcoin’s.

Historical Bitcoin electricity reconstructions put a comparable ~0.17 GW footprint around 2014–15, roughly five to six years after its genesis. Pearl got there in four months, or 18x faster. That is the advantage of inheriting an infrastructure footprint instead of having to bootstrap one from scratch. Speaking of infrastructure footprint, this is when the numbers start to get pretty crazy in Pearl’s favor. Much like how the TAM for Bitcoin’s security is the install base and subsequent power draw from ASICs, the TAM for Pearl’s security is its power draw from the global GPU install base.
McKinsey projects roughly 156 GW of AI-related data-center capacity by 2030. That power pool would be more than 9x Bitcoin’s current electrical footprint. If overhead goes low enough, Pearl can recruit an existing machine base instead of subsidizing a bespoke one from scratch.

It should be clear that Pearl has a vastly larger pool of power to draw from to secure its network than Bitcoin does.
So much for the “Bitcoin singularity”

There can only be one decentralized crypto asset. Why would you use the 2nd most secure chain as your store of value?
You would only ever want to use the most secure. The economic blackhole of Bitcoin is evaporating.

“There’s one crypto asset and it’s called Pearl.”
Another way to look at this is ASIC capex vs AI capex. Would you rather have a decentralized currency secured by ASIC capex, or a decentralized currency secured by AI capex? (which, by the way, is the largest capex buildout in human history).
Since 2013, we can estimate from Bitmain revenue history that cumulative Bitcoin ASIC capex has reached roughly $34.5B. Goldman Sachs now estimates cumulative global AI investment will reach $1.8 trillion by the end of 2026 — including roughly $1 trillion in 2026 alone.
That's more than a 50x difference. AI is now deploying nearly 30x Bitcoin's entire estimated historical ASIC capex every single year.
Data center capex is forecasted to reach $3 - $6.7 trillion by 2030.
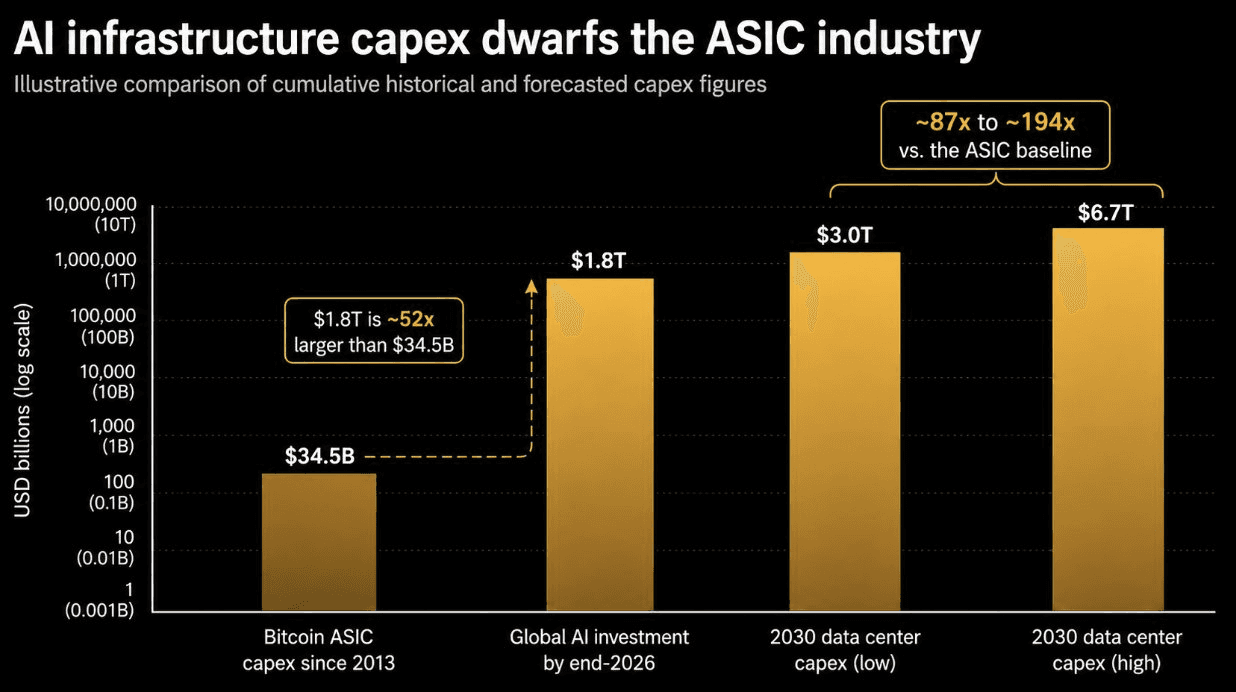
This further widens the capex gap to nearly 200x on a forward looking basis. So can Pearl be 200x more secure than Bitcoin?
It’s not quite that simple unfortunately. 100% of Bitcoin ASIC capex goes towards securing the network, because there is no other use for that hardware aside from mining Bitcoin. 100% of AI capex will obviously not go towards mining Pearl, but the TAM speaks for itself. Pearl only needs to attract 0.5% of near-term forecasted AI capex to eclipse Bitcoin’s total ASIC capex.

That’s pretty damning for Bitcoin. I don’t have a crystal ball, but what happens to Bitcoin in a world where Pearl has more hashrate, power draw, and capex securing it? This would truly be a come to God moment for Bitcoin maximalists.
If Pearl succeeds in its mission to be decentralized AI backed money, the investment opportunity speaks for itself. It would replace Bitcoin as the hardest money ever created.
Compute Financialization
Pearl aspires to be financialized compute. Currently AI goes in, Pearl comes out. But the long-term goal of Pearl is to become deeply embedded within the AI economy, so that the reverse is also true. Pearl goes in, AI work comes out. This completes the loop.
Pearl’s whitepaper explicitly describes a future marketplace that could match compute supply and demand and eventually settle compute contracts natively. In that world, Pearl is not merely a mining reward. It becomes a monetary base for compute.
This matters because it creates endogenous demand for the Pearl. Inference providers mine PRL; AI customers acquire or spend PRL; the token links a heterogeneous pool of compute into one financial unit. Pearl as “AI money” stops being a meme and becomes actual market structure.
Revelation
So, what should Pearl be worth? There are two relevant valuation methodologies.
1. SoV Monetary Premium (ie “AI Bitcoin”)
2. Compute Monetary Base
SoV
The cleanest bull case is that Pearl starts earning monetary premium as an alternative proof-of-work / store-of-value reserve asset. You do not need it to replace Bitcoin to get a silly return from the current base (although it could). The hunt for new SoVs is already underway; institutional allocators are increasingly diversifying from Bitcoin and looking at alternative store-of-value assets.
Zcash ($ZEC) is a live comp because it shows how quickly an alternative SoV asset can move from “interesting niche” to a non-trivial percentage of Bitcoin’s monetary value when the market finds a differentiated narrative. ZEC has capitalized on privacy and quantum resistant factors to emerge as a promising alternative to Bitcoin, and as of late August 2026, ZEC’s market cap has been roughly $13–14 billion while Bitcoin is roughly $1.56 trillion — about 1% of Bitcoin. Pearl’s market cap is only around $70–80 million and can go on a similar run. Pearl at 1% of Bitcoin would imply an FDV of $16B, or a price at $7.61 per Pearl, which is a 30x from today’s prices.
However, Pearl is a PoW blockchain still in its infancy. Less than 15% of the network has been mined thus far. Therefore, FDV is the wrong denominator for a short-to-medium term investment. Based on roughly 525M PRL outstanding around Pearl’s first anniversary, or about 25% of max supply, if Pearl achieves a valuation of 1% of Bitcoin’s within its first year, this would actually imply a token price of $30.50/Pearl. Or a 117x from today’s prices.
If Pearl succeeds, it should be a top 10 crypto asset.

Compute Monetary Base
S&P Global forecasts AI inference infrastructure revenue alone growing from $101B in 2025 to $532B in 2030.
If Pearl becomes deeply embedded in the inference economy, some portion of that compute should eventually be priced, collateralized, prepaid, or settled in PRL. The key question is how much PRL monetary base is required to support a given amount of compute activity, and what does that make Pearl worth?
Fortunately, we’ve got a simple formula for that: Required PRL monetary base = annual PRL denominated compute GMV ÷ token velocity
The key variable is token velocity. Can we accurately estimate this? In Pearl’s case velocity is equal to compute inventory duration.
For example, if the AI economy does $25B of annual compute business in PRL, how many days of that future compute spend does the ecosystem want to warehouse in PRL at any given time?
The math is the same:
PRL monetary base = annual compute GMV × average inventory days / 365
Which means:
Velocity = 365 / average inventory days
Twenty-times velocity simply means the market carries about 18 days of compute spend in PRL. 10x means ~37 days. 5x means ~73 days. 2x means roughly six months. 1x means the market is carrying an entire year of compute demand as monetary inventory.
So what is the right velocity number to value Pearl? We can look at analogous markets as a starting point.
Starbucks is a giant closed-loop stored-value economy. During FY2025, approximately $15.2B of card and loyalty balances were redeemed against an average stored-value/loyalty liability of ~$1.74B. That works out to roughly 8.8x annual turnover, or about 42 days of stored purchasing power sitting in the system at any given time.
Airline miles sit at the opposite extreme. Delta had roughly $9.0B of average SkyMiles deferred-revenue liability during 2025 against about $4.46B of miles redeemed, implying turnover of only ~0.5x, or nearly two years of stored purchasing power. Delta itself says the majority of newly issued miles have historically been redeemed within two years.
In the middle of this spectrum we can also look to BTC and ETH, as they both provide guaranteed inclusion to blockspace and native settlement within their respective networks. Both assets have similar velocity, Glassnode reports them at 0.0100 and 0.0103 per day, respectively. This roughly translates to 3.7x annualized turnover (or about 100 days of inventory) for both.
This creates a pretty wide, but economically reasonable range for Pearl.
At one extreme, PRL is basically a payment rail. The customer buys PRL five minutes before an inference request, spends it, the provider receives it, and immediately sells it. Velocity could be enormous.
At the other extreme, PRL becomes something closer to compute inventory: inference providers keep it as working capital, customers pre-fund future workloads, providers post it as collateral, enterprises hold it against contracted compute requirements, and large AI companies simply retain a portion of the PRL they naturally produce. Then velocity would collapse toward 1–5x.
And eventually the line between “compute inventory” and “money” starts to disappear.
The Compute Forward Curve
There is another variable that should influence how much compute inventory people want to hold: the forward curve for compute itself.
This market barely existed a year ago and is already starting to financialize. Silicon Data
now publishes standardized GPU forward curves out to 36 months; Ornn publishes transaction-based spot indices and forward marks; Kalshi launched market-implied compute forward curves across H100, H200, B200 and other hardware accelerators.
Today, much of the standardized curve is flat-to-backwardated. Silicon Data's July curve showed B200, H100 and A100 term pricing roughly 8–15% below spot over 36 months, reflecting expectations that supply growth and newer hardware will push the cost of a unit of compute down over time. Kalshi similarly shows B200 compute in backwardation, with legacy Hopper curves materially flatter.
This data should push Pearl toward higher velocity.
E.g. If I expect compute to be cheaper six months from now, why would I warehouse six months of future compute purchasing power today? I would rather keep my dollars, earn yield, and acquire PRL closer to when I actually need the compute.
But this lacks nuance. We need to flip the curve.
Travis Good of Ambient recently posted an excellent graph outlining the fact that long-term contracted compute prices are in contango, vs spot pricing which has remained soft.

The guaranteed access compute market can move into persistent contango because power is scarce, inference demand overwhelms GPU supply, or hyperscalers begin consuming every incremental hardware accelerator before it reaches the spot market. If future compute is expected to be substantially more expensive than compute today, securing future purchasing power suddenly becomes valuable. Buyers should be willing to lock prices, pre-fund compute, reserve capacity, or hold whatever asset gives them reliable future access. A contangoed compute curve would make locking future purchasing power by holding PRL more valuable.
That should lower PRL velocity.
The forward curve becomes one of the most important determinants of how much PRL users want to hold.
Bitconia → Fortessia → Duplexia is also a Velocity Curve
This is where Pass's framework becomes relevant again.
In Bitconia, almost everyone is effectively a standalone miner. A miner buys GPUs and electricity for the purpose of producing PRL.
PRL is something miners produce specifically in order to monetize. There is little structural reason to keep it. Useful work is negligible, compute settlement is negligible, and velocity should be extremely high.
As Pearl moves into Fortessia, useful inference providers enter the network. This changes the balance-sheet behavior completely.
A Together AI-style useful miner is not relying on PRL to pay its GPU bill. Its inference customer is already paying for the underlying computation. PRL becomes incremental revenue produced alongside its normal business.
That miner does not need to sell every Pearl it mines.
As useful miners become a larger share of network hashrate, the reflexive mine-and-dump pressure should therefore fall. At the same time, these businesses naturally have future compute liabilities: contracted customers, reserved clusters, forward capacity requirements, working-capital needs. PRL starts becoming an asset that is useful to keep around rather than an asset that must immediately be converted back into fiat.
Velocity falls.
By Duplexia, the relationship reverses completely. AI companies are not merely mining Pearl on the side. Pearl is becoming part of the commercial plumbing of the compute economy itself.
Providers earn it. Customers spend it. Marketplaces settle in it. Contracts can be denominated in it. Providers hold it against future obligations. Customers hold it against future workloads.
This means Pearl's velocity should not be treated as a static assumption. Velocity itself should decline as Pearl succeeds.
The same fundamental adoption that increases compute GMV should simultaneously increase the amount of PRL the ecosystem wants to warehouse against that GMV.
Pearl therefore potentially gets two valuation multipliers as it travels from Bitconia into Duplexia:
more compute settles in PRL × each dollar of PRL turns over more slowly.
That is how the monetary base can expand much faster than compute GMV itself.
An Illustrative Pearl Maturity Curve:

You can see how violently valuation changes when GMV growth and declining velocity happen together.
For example, moving from $10B of annual compute GMV at 10x velocity to $50B at 2x velocity is only a 5x increase in underlying compute activity, but the required monetary base jumps from $1B to $25B — 25x.
We can also separate the two variables and look at the entire sensitivity range:

If Pearl is simply another payment rail for a few billion dollars of spot inference, the compute valuation isn't particularly exciting. At $5B of GMV and 20x velocity, it supports only ~$250M of monetary base, or roughly $0.48/PRL on this framework.
If Pearl gets to Fortessia and begins supporting tens of billions of dollars of compute while providers carry a few months of PRL inventory, the numbers move into the $5–25B monetary-base range, or roughly $10–50/PRL using the first-anniversary supply denominator.
And if Duplexia actually happens: useful miners dominate, PRL settles a meaningful percentage of the global inference economy, enterprises hold six to twelve months of compute purchasing power, and providers increasingly treat PRL as working capital or a treasury asset, that gets us to a $50–100B+ compute monetary base, and a price target of $190+.
At low velocity the two frameworks begin converging. If AI companies are willing to hold a year or more of PRL because they regard it as durable future purchasing power, collateral and treasury reserve, that behavior itself is monetary premium.
That is Duplexia.
The Last Temptation
Pearl has already done the hard part. The low overhead 2:1 kernel. This is the significant innovation possessed only by Pearl, giving them a real shot at broad adoption.
But the job’s not done.
Today, Pearl’s PoUW consensus still runs through its W7A7 integer quantization scheme. You can think of this as matrix multiplication of whole numbers only. That works, but the frontier of AI hardware is increasingly optimized around low-precision floating point. Floating point numbers support decimal places and have more precision than integers, and frontier LLMs rely on floating point.
The goal of the next Pearl hardfork is to support state-of-the-art low-precision workloads without forcing them through the existing integer adaptation.
This is Pearl’s crucible. Pearl cannot ask the AI industry to freeze itself in whatever numerical format happens to make Pearl convenient. Pearl has to chase the AI stack, not the other way around.
Fortunately, the team already has a draft proposal for native floating-point PoUW. Pearl Improvement Proposal 3 (PIP-3) replaces the current INT protocol with an FP protocol built around FP8 quantization. The change is non-trivial, and successful execution is required for meaningful hyperscaler and neocloud adoption.
If that works, the next bottleneck is integration.
Once FP integration is live, Pearl needs to crack closed-source adoption. Right now, in order to “pearlify” a model and do 2:1 operations on it, Pearl Research is meaningfully involved in quantizing the models into their specific INT format. This has thus far limited adoption to open-source labs, because obviously no closed source lab would allow Pearl Research inside their models to help quantize them. With FP live, “Pearlifying” becomes a generalizable drop-in kernel, and any lab will be able to integrate without needing assistance from the Pearl team. Open-source inference got Pearl to Fortessia, but closed-source hyperscaler integration would kingmake Pearl.
One reason I take the technical roadmap seriously is the team behind it. Pearl was founded by Omri Weinstein and Ilan Komargodski , with deep backgrounds spanning academic cryptography, Nvidia Nvidia, VAST Data , machine learning and zero-knowledge systems. Rafael Pass, one of the leading academic cryptographers working on PoUW economics, is also directly involved with the project. Despite the very public team, Pearl itself was fair launched with no VC token allocation or investor overhang.
Pearl’s Adoption isn’t Pre-Ordained
The Pearl thesis does not require everything to go right. It does require a few things not to go catastrophically wrong. These are the key risks to the adoption path:
Overhead stops falling. Five percent is already impressive. Five percent is also not zero. If Pearl’s floating-point protocol cannot keep pace with FP8, FP4, new NVIDIA architectures, new quantization schemes and whatever inference kernel wins next, the problem compounds. An AI company does not care that Pearl mining is clever if enabling it makes its core product materially worse. The PRL subsidy always has to be worth more than the throughput loss, engineering burden and operational risk.
Useful miners never become the marginal producer. Together AI proves something extremely important: genuine customer inference can mine Pearl. That kills the argument that useful mining is merely theoretical. It does not, however, prove that useful miners will dominate the network. The whole natural-selection thesis depends on useful miners eventually having a lower effective cost than synthetic ones. If that never happens, Pearl becomes much less interesting.
Pearl never becomes money. AI companies could love mining Pearl and still have absolutely no interest in holding Pearl. Pearl’s own whitepaper is remarkably explicit about this. It says the value of the token as a store of value ultimately depends on the expectation that it becomes a means of payment for a sufficiently large set of users. The forthcoming compute marketplace is not an optional roadmap item. It is where the monetary thesis either becomes real or dies.
The hardware game turns against Pearl. Pearl argues that it is economically ASIC-resistant because matrix multiplication is already the primary optimization target of GPUs and TPUs, and a machine designed solely to mine Pearl would sacrifice the valuable inference revenue available to a general AI accelerator. The whitepaper carefully calls this “plausible” ASIC resistance, but the nightmare scenario is somebody still finding a specialized architecture that produces Pearl-valid work so much more efficiently than general-purpose AI hardware that the efficiency gain overwhelms the duplex miner’s inference revenue. Then Pearl’s game theory approach falls short and the useless miner becomes the cheapest miner again.
Pearl fails to ossify. The protocol is not yet ossified. In fact, there have been five activated mainnet consensus changes between genesis and August 11. Most notably, a recent soft fork to support Mixture-of-Expert (MoE) proofs became legal at block 71,935, but this led to miner exploits where they could spoof hashrate and win a disproportionate amount of block rewards. Thankfully this issue was discovered and the MoE upgrade was temporarily disabled 41 days later at block 91,630. Other protocol changes include a rank-penalty soft fork activated at 96,251 and a salted noise-seed hard fork followed at 99,000. Pearl needs to use this period to break things, fix them, finish the architecture and eventually earn the right to ossify.
Come get Pearlified with me
Bitcoin proved useless computation could become money.
Pearl is betting that useful computation can become harder money.
If overhead approaches zero, useful AI providers become structurally advantaged miners because someone else already paid for the compute. The block reward becomes a subsidy on inference. Lower inference prices create more demand. More demand creates more duplex compute. More duplex compute hardens Pearl, and eventually the asset being produced by the machines becomes the asset used to buy the output of those same machines.
AI produces the money. The money buys the AI. The loop closes.
At that point Pearl is the money of compute.
And if the monetary network secured by the world’s AI infrastructure ultimately becomes harder to attack than the one secured by warehouses full of single-purpose ASICs, then Michael Saylor may turn out to have been right.
There is no second best.
He may have just picked the wrong one.
Come get Pearlified with me.
Thanks and acknowledgements
Huge thanks to Pearl Research Labs @prlnet for their feedback and guidance putting together this research piece. Their academic insights helped make this paper what it is today. Also shoutout @tulipking, my close friend and confidant, whose advice and feedback greatly influenced the tone and style of this paper.
Disclaimer
The views expressed herein are solely those of the author and are provided for informational purposes only. They do not constitute investment, legal, tax, or other professional advice, and should not be relied upon as the basis for any investment decision. References to specific companies, protocols, tokens, or sectors are illustrative only and do not constitute a recommendation or solicitation to buy or sell any security, token, or other asset. The author is an investor at No Limit Holdings, a venture capital firm that invests in blockchain and digital asset-related businesses, and No Limit Holdings and/or its affiliates may hold positions in, or have other economic interests in, certain companies, protocols, tokens, or sectors discussed herein.
© 2024 No Limit Holdings. All rights reserved.